Every year, the aviation industry installs more RFID tags, BLE beacons, and GPS trackers on ground equipment, ULDs, baggage systems, and MRO shipping containers. And every year, I ask the same question to ops directors and fleet managers: can you show me the productivity data from your tracking deployment? The room goes quiet. Aviation asset tracking productivity gains are real. The evidence is there, scattered across field cases from Amsterdam to Sydney. But most organizations never establish the baselines that turn “we can see our stuff” into an ROI number a CFO will defend.
That gap between visibility and proven productivity is where budgets die. If your next capital request for asset tracking cannot demonstrate reduced search time, fewer duplicate purchases, or faster turnaround, finance sees a cost line. Not an investment. I have spent over 15 years deploying IoT tracking across aviation supply chains, and the pattern is consistent: the technology works, but the measurement discipline around it rarely does.
This article breaks down what the field evidence actually shows, where it falls short, and how to structure a deployment that generates numbers you can put on a slide without flinching.
What Counts as a Productivity Gain in Aviation Asset Tracking
Let me be direct: seeing a dot on a dashboard is not a productivity gain. Visibility is infrastructure. Productivity happens when visibility changes someone’s behavior, and that behavior change saves time, money, or both.
In aviation, the gains sort into five operational buckets:
- Search time reduction. Ramp crews and MRO technicians spend less time hunting for equipment, tools, or shipping containers. In maintenance, the industry calls this wrench time, and it sits at roughly 35% across the sector. The rest is walking, waiting, looking.
- Utilization improvement. Assets serve more turns per day or loads per cycle instead of sitting idle in the wrong place. A tug parked at Terminal C while Terminal A is short a unit is invisible waste until you track it.
- Fleet right-sizing. Organizations buy fewer assets because existing ones are redeployed where demand is. This is the big money, and it is measurable.
- Recovery acceleration. Mishandled bags, missing ULDs, and delayed parts are located faster. Time-to-recovery drops, and with it, the cost of workarounds.
- Duplicate elimination. You stop purchasing replacements for assets that are not actually lost. They were just invisible.
Each of these maps to operational dollars. But each requires a different baseline measurement, and skipping that step is the single most common mistake I see in aviation tracking deployments.
The Evidence, Asset Class by Asset Class
There is no single credible “aviation asset tracking saves X%” figure that applies across the board. Anyone quoting one is selling. The evidence is real, but it is specific to asset classes and operational contexts. Here is what the field data actually says.
Baggage
Baggage has the largest visible cost pool. SITA’s 2026 reporting shows mishandling rates fell 23% in 2025, with 24 million bags still mishandled at a total industry cost of $6.3 billion. That is roughly $260 per mishandled bag and about 15% of industry profit. Delayed bags alone accounted for 18.2 million units and approximately $4.4 billion in cost, representing 75% of the total mishandled volume.
The critical detail: transfers caused 39% of mishandling. That is a coordination problem as much as a technology problem. A tag on a bag does not help if the receiving handler’s system cannot see the event or act on it in real time. IATA’s Resolution 753 framework set the standard for tracking at check-in, loading, transfer, and arrival. By end of 2025, 80.1% of the 256 in-scope airlines had an implementation plan. Plan, not deployment. The distinction matters.
Ground Support Equipment
GSE tracking is where the fleet right-sizing argument gets interesting. A September 2026 report from Blackhawk describes more than 10,000 GSE assets tracked across 60-plus airports, with data enabling reductions of up to 10% in some asset classes and active redeployment between airports. In an equipment market valued at over $10 billion in 2026, a 10% fleet reduction at a single large ground handler represents serious capital avoidance.
At Amsterdam Schiphol, Undagrid’s deployment for Facilicom reported less time searching for equipment, fewer PRM-service handover delays, and faster defect resolution. The limitation: no audited before-and-after labor figures were published. A separate Australian case tracked 5,000 assets across 12 airports and described lower maintenance costs and a smaller fleet, also without publishing a dollar figure.
This is the pattern in GSE tracking. Qualitative improvements are widely reported. Audited, controlled ROI studies are rare.
ULDs
Pooled ULD containers move across airlines and continents, which makes them a natural fit for digital tracking. Unilode reported 100,000 digital ULDs in service supporting 40 management customers, with 75% fewer unreported units among the digitized fleet and loss rates of 0.01%. Their Super Sentinel program, targeting 220,000-plus ULDs during 2026, aims to locate containers even outside the fixed-reader network.
The productivity logic is clean: fewer unreported ULDs means fewer emergency procurements, fewer lease penalties, and faster cycle times. When a ULD disappears from the system for weeks, someone is paying for a replacement or an expedited workaround. Visibility eliminates that cost.
MRO Parts and Packaging
KLM Engineering & Maintenance used RFID to track reusable packaging for airplane parts and reported a 50% reduction in packaging costs. That is packaging, not total maintenance expense. The distinction is easy to miss in a headline, but it is important: a 50% saving on the cases and boxes that move parts between facilities is material, yet it is not the same as a 50% reduction in MRO cost.
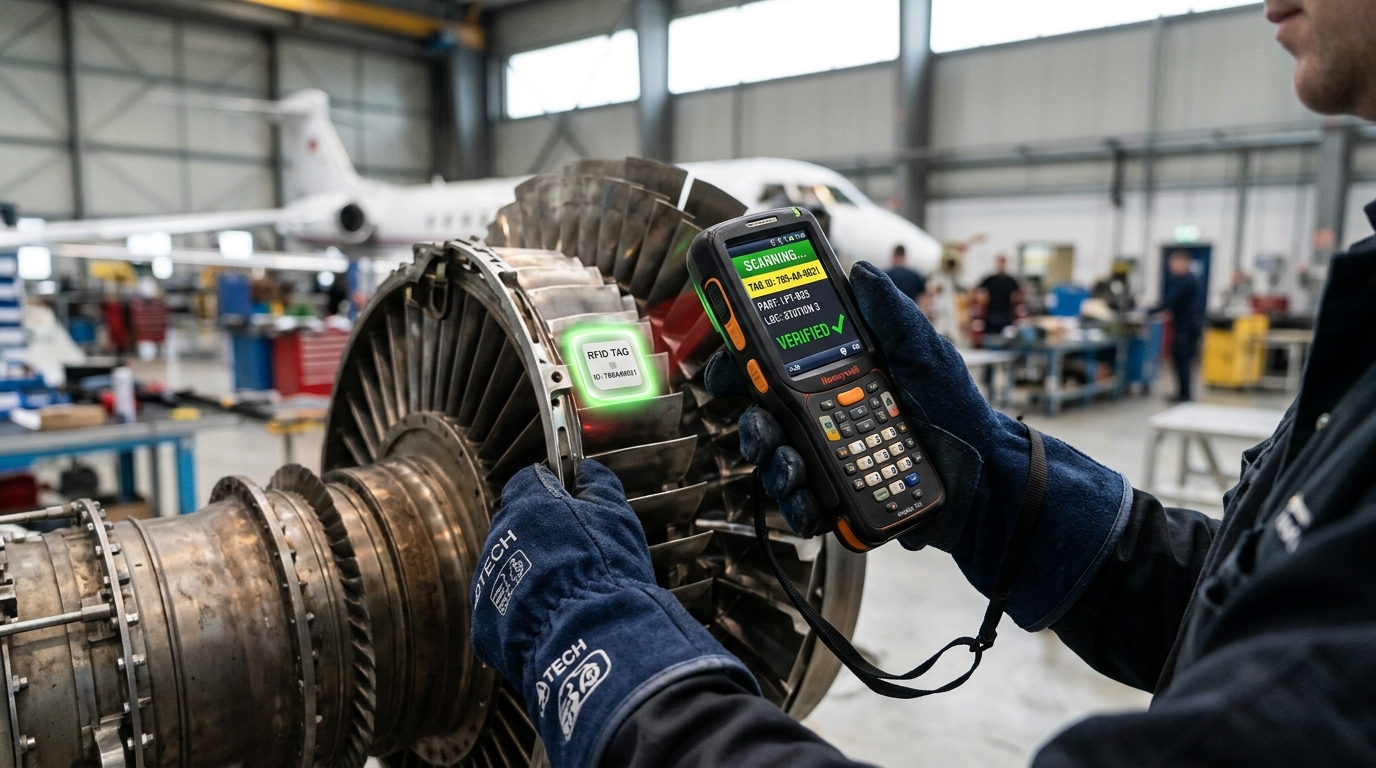
Delta TechOps deployed RFID across 923 active aircraft tails and 57 stations. The most revealing outcome was not a labor reduction but a data quality improvement: the system exposed incorrect tracked dates and configuration differences that manual processes had missed. That is a compliance and safety benefit, harder to monetize but arguably more consequential.
Summary Table
| Asset Class | Documented Gain | Evidence Strength | Key Caveat |
|---|---|---|---|
| Baggage | 23% reduction in mishandling rate (2025) | Strong (SITA industry data) | $6.3B still leaks; transfers remain the primary failure point |
| GSE | Up to 10% fleet reduction in some classes | Moderate (vendor-reported, multi-site) | No audited, controlled ROI published |
| ULDs | 75% fewer unreported units; 0.01% loss rate | Moderate (operator-reported) | Figures from a single pool operator |
| MRO Packaging | 50% packaging cost reduction | Strong (named case, specific metric) | Packaging cost ≠ total maintenance cost |
| MRO Data Quality | Configuration and date errors identified | Moderate (presentation, no dollar figure) | Valuable but hard to monetize directly |
The Measurement Problem Most Vendors Will Not Mention
Here is something I tell every customer before we scope a project: the technology is the easy part. The hard part is proving what it changed.
There are structural reasons why clean aviation asset tracking ROI numbers are rare, and understanding them will save you from both overselling internally and underfunding externally.
No pre-deployment baselines. Most organizations start tagging assets before measuring what the world looked like without tags. If you do not know that ramp crews spent an average of 14 minutes per shift searching for belt loaders before tracking, you cannot prove the number dropped to 4 minutes after. You just have a number with no anchor.
Fragmented custody. Bags, ULDs, and even GSE pass through multiple operators. An airline, a ground handler, and an airport authority may all touch the same asset in a single turn. When something improves, three parties can claim credit or none can isolate their contribution. SITA’s data showing transfers as the source of 39% of baggage mishandling is a symptom of this fragmentation.
Vendor incentive structure. Tracking vendors, including hardware suppliers like us, have an incentive to publish “up to X%” figures from best-case deployments. Those numbers are directional. They are not audited benchmarks. Treat them as hypotheses to test, not promises to bank on.
Blended benefits. Tracking often improves data quality, compliance posture, and regulatory readiness alongside the productivity gains. Delta TechOps finding configuration errors is a perfect example. That benefit is real and potentially worth more than a few saved labor hours, but it does not fit neatly into a productivity spreadsheet.
None of this means you should not deploy tracking. It means you should deploy it with measurement rigor built into the project from day one.
Six Baselines to Set Before You Tag Anything
If you want aviation asset tracking productivity gains you can defend, measure these six things for 30 to 60 days before a single tracker goes live:
- Minutes spent searching per shift. Shadow two to three crew shifts across different roles (ramp, MRO floor, baggage). Record how much time people spend looking for assets versus using them. This is your wrench-time proxy.
- Percentage of assets visible at any given time. Take a random snapshot: how many of your GSE units, ULDs, or tool kits can you locate within five minutes right now? That number is usually lower than anyone expects.
- Utilization rate. For GSE: turns per day. For ULDs: loads per cycle. For packaging: round trips per quarter. Tracking only creates value if it moves these numbers.
- Late departures or delayed maintenance jobs attributable to missing equipment. Pull data from ops logs. If a push-back was delayed because no tug was available, or an MRO job slipped because a shipping container was missing, that is cost you can attribute.
- Annual losses and write-offs. Insurance claims, depreciation write-downs on “lost” assets, emergency purchase orders. This is the easiest number to find in finance systems and often the most shocking.
- Replacement purchases that redeployment could have avoided. Cross-reference procurement data with asset location gaps. If Station A bought five new dollies last quarter while Station B had eight sitting idle, that is your fleet right-sizing opportunity.
Measure the same six metrics 90 days after deployment. The delta between pre and post is your productivity case. It will not be a single headline number. It will be six specific improvements, each tied to a cost line the finance team already tracks.
Matching Technology to the Bottleneck, Not the Brochure
One of the most expensive mistakes in aviation tracking is buying a single technology platform for every use case. A container on a trans-Pacific route needs different coverage than a torque wrench in Hangar 3. Here is how the technologies actually map to operational needs in 2026:
| Technology | Best For | Practical Constraints |
|---|---|---|
| RFID (passive and active) | Identity and event capture at instrumented points: baggage checkpoints, parts traceability, ULD gate scans. IATA reports 99 to 100% read rates for baggage RFID. | Requires reader infrastructure at each checkpoint. No continuous location between readers. |
| BLE (Bluetooth Low Energy) | Low-power fleet-wide tracking of non-powered GSE and tools where approximate location is sufficient. | Range and accuracy depend on beacon density. Battery management across large fleets adds operational overhead. |
| UWB (Ultra-Wideband) | Precise indoor positioning. A 2025 study reported approximately 0.35 m location uncertainty under controlled conditions. Useful for high-value tool locations in hangars. | Infrastructure cost is higher per square meter than BLE. Not practical for wide-area ramp coverage. |
| GPS/Cellular | Wide-area tracking for assets that move between airports, go off-ramp, or cross national borders. Devices like the Oyster3 or Remora2 fit this profile well. | No indoor accuracy. Battery life trades off against reporting frequency. |
| Satellite/ADS-B | Aircraft flight tracking and wide-area safety surveillance. A different problem entirely from GSE or tool tracking. | Do not confuse aircraft surveillance forecasts with ground-equipment tracking ROI. |
For airfreight-specific applications, regulatory compliance adds another layer. The FAA’s July 2026 update to AC 119-2A addresses onboard RFID use, requiring that tags not interfere with adjacent aircraft systems and that operators document procedures and deployment schedules. Trackers intended for air cargo, like the Thingfox T2 with DO-160 certification, exist precisely because consumer-grade devices are not designed for the electromagnetic and pressure environment of a cargo hold.
The point is not to pick the “best” technology. The point is to match the technology to the specific bottleneck you baselined in the previous section. If your biggest cost leak is search time on the ramp, BLE or GPS cellular solves it. If it is parts traceability in MRO, RFID at instrumented points solves it. If it is both, you need a layered deployment, and you should budget accordingly.
The Inertia Tax: What Waiting Costs in 2026
I hear a version of the same objection regularly: “We will track next year, once the budget frees up.” Here is the problem with that logic.
Aviation parts inflation has been running at roughly 7.7% annually. Every duplicate purchase you make this year because you cannot see where your existing assets are costs 7.7% more than it would have last year. That is a compounding loss, not a flat one.
The technician shortage compounds it further. The industry faces a projected deficit of 60,000 maintenance technicians by 2029. Every minute a skilled tech spends walking instead of wrenching is a minute you cannot hire back. Tracking does not fix the labor shortage, but it stretches the labor you have.
Regulatory momentum is also accelerating. IATA’s Resolution 753 continues to push toward complete baggage visibility. The FAA’s updated RFID guidance signals that onboard and near-aircraft tracking systems are expected to follow documented, safety-compliant procedures. Organizations that delay deployment are not just missing productivity gains. They are falling behind a compliance trajectory that will eventually become non-optional.
There is also a less obvious cost: the longer you wait to establish baselines, the harder it becomes to isolate what tracking changed versus what changed from other operational improvements running in parallel. The cleanest ROI stories come from organizations that measured first and deployed second, in that order.
And for organizations under ESG reporting pressure, tracked assets are reused more and wasted less. That connection between asset visibility, reduced material waste, and sustainability metrics is increasingly relevant for airline procurement and investor reporting. It is not the primary reason to track, but it is a reason that matters to stakeholders outside operations.
Frequently Asked Questions
What types of assets does aviation asset tracking cover?
It spans passenger baggage, ground support equipment (tugs, belt loaders, dollies), ULD containers and pallets, MRO tools and parts packaging, and aircraft in flight. These are distinct operational problems with different tracking technologies, different custody chains, and different ROI mechanisms. Treating them as one market leads to poorly scoped deployments.
What productivity gain should I expect from tracking GSE?
Published field cases report qualitative improvements in search time and equipment availability, with one multi-airport deployment documenting up to 10% fleet reductions in some asset classes. There is no defensible industry-wide benchmark. Your gain depends on your current fleet utilization, station geography, and whether you set baselines before deployment.
Is RFID the only compliant technology for aviation tracking?
No. IATA’s Resolution 753 defines tracking events, not the technology used to capture them. RFID delivers 99 to 100% read rates at instrumented checkpoints, but BLE, UWB, and GPS cellular all serve different use cases. The FAA’s AC 119-2A provides guidance for onboard RFID specifically, but asset tracking on the ramp or in warehouses uses a broader technology mix.
How long does it take to see measurable results?
With proper baselines in place, most organizations can demonstrate measurable changes in search time, utilization, and fleet visibility within 90 days of deployment. The financial ROI case (fleet right-sizing, avoided purchases, reduced write-offs) typically requires six to twelve months of data to prove convincingly to finance teams.
Do consumer tracking devices like AirTags work for aviation operations?
Consumer devices are entering baggage recovery workflows. Virgin Atlantic enabled Apple Find My sharing in early 2025, and SITA integrated Google Find Hub into WorldTracer in 2026. These tools help locate delayed bags but do not replace airline custody scans, are not certified for all cargo environments, and face FAA battery restrictions for checked baggage. Operational tracking requires purpose-built, certified hardware.
What is the biggest mistake organizations make with aviation asset tracking?
Deploying trackers without pre-deployment baselines. Without knowing your starting point for search time, utilization, and asset losses, you cannot prove what changed. The second most common mistake is treating visibility as the endpoint. A live map that nobody acts on produces zero productivity gain.
If your tracking deployment is generating a map but not changing decisions, that is the gap worth closing. We work with airlines, MROs, and ground handlers to build tracking systems that produce defensible productivity numbers, not just dashboards. Talk to our team or reach us at info@datanetiot.com.

 +1 508 292 2210
2 Responses